One of our readers asked us: “I’ve set up a limited company – how do I draw money from my company to pay myself?”
Let’s start by reminding ourselves that when you have a limited company, you and the company are separate legal entities, and you will have a separate business bank account. When you provide services to a client, your business invoices them, and the payment goes into your business bank account.
So how do you get that money into your personal account?
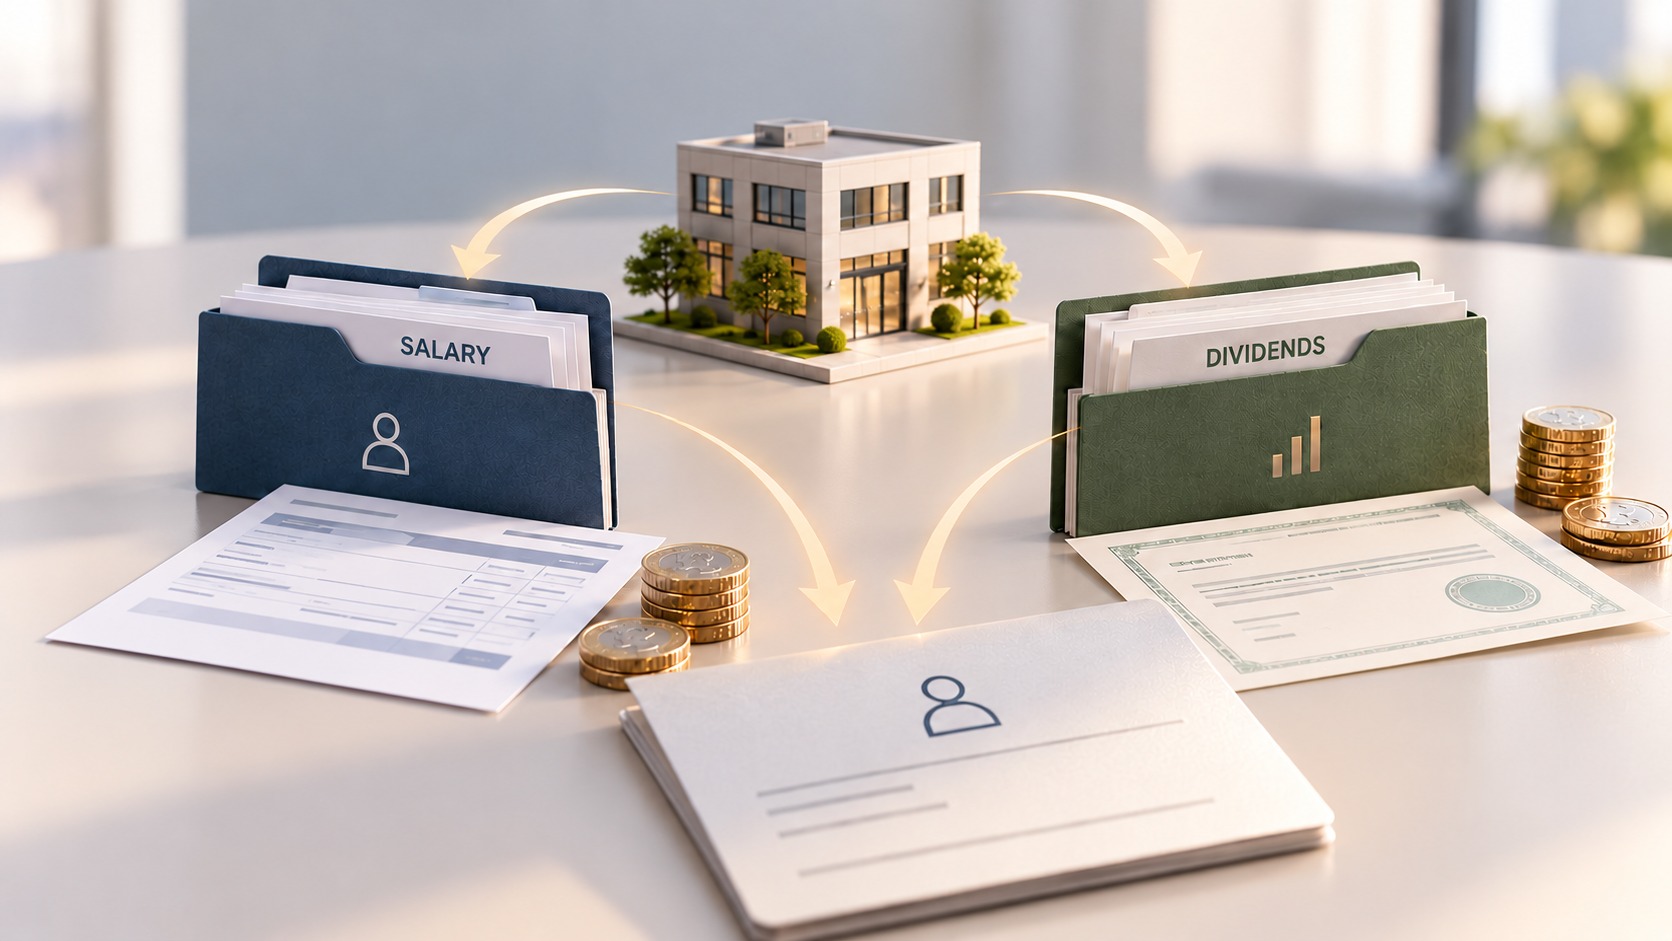
Most limited company directors pay themselves through a combination of salary and dividends, but you should be aware of several rules.
Paying yourself a salary
Talk to your accountant about the most tax-efficient salary options so you can decide how much to pay yourself and other employees.
When you run payroll (usually monthly), your accountant (and accounting software) will calculate how much National Insurance and income tax you need to pay to HMRC. This includes employer’s NI (if applicable), as well employee’s NI.
You will need to pay this directly from your company, which is easy to do by bank transfer.
How often you need to make those payments depends on how much NI and tax you owe.
For example, if the combined PAYE tax and National Insurance amount that you owe averages £1,500 or more a month, you will normally be required to make monthly payments to HMRC. Companies with smaller PAYE liabilities can usually arrange to pay quarterly.
You can transfer your salary from your limited company’s account to your personal account, after deducting employee tax and National Insurance. Your company will also need to operate payroll and report the salary payments to HMRC.
Paying yourself through dividends
Often, a combination of salary and dividends (rather than just salary) can be the most tax-efficient way to pay yourself, and it’s worth asking your accountant (or talking to us here at Integro) whether this could be in your best interest.
The dividend would come out of your business profit, but before paying yourself dividends, always account for other expenses that need to come out of the profit, such as Corporation Tax, so you don’t leave yourself short.
Dividends can only be paid from profits available for distribution, after allowing for Corporation Tax and any previous losses. You also need to consider the other shareholders in your company, as dividends are normally paid according to the rights attached to each class of shares.
The salary part is taxed at source (because you’re registered for PAYE, as mentioned above), but you’ll normally pay tax on dividends through your personal tax return, where required.
For the 2026/27 tax year, the dividend tax rates are:
- 10.75% for basic rate taxpayers.
- 35.75% for higher rate taxpayers.
- 39.35% for additional rate taxpayers.
There is also a £500 annual dividend allowance, meaning the first £500 of dividend income falling within the allowance is taxed at 0%. Any additional dividend income is taxed according to your tax band.
To learn more about the most tax-efficient combination, read our guide to salary vs dividends for contractors.
Our limited company dividend guide covers the rules around declaring dividends, how they’re taxed and the records you need to keep.
Can I just transfer money from my company account?
You can transfer money from your limited company to your personal bank account, but you need to be clear about what each payment represents.
If it’s your salary, the payment should be recorded through payroll.
If it’s a dividend, the company must have sufficient profits available to pay it, and you need to complete the appropriate dividend paperwork.
You can also reimburse yourself for legitimate business expenses you paid personally, or recover money you previously lent to the company.
If you take money out of the company without classifying it as salary, a dividend, or another legitimate payment, it will usually be recorded in your director’s loan account.
This isn’t necessarily a problem, but if you owe money to your company at the end of its accounting period, you may face additional tax consequences if you don’t repay the loan within the relevant deadlines.
Also remember that the amount in your company bank account isn’t necessarily available for you to withdraw.
If you have, say, £20,000 in your business current account, you need to account for any future liabilities, e.g. Corporation Tax, VAT, and any other outstanding liabilities. If you’re unsure, check your accounting software balances, and ask your accountant before you declare a dividend.
Keeping records of your dividend payments
Every time your company makes a dividend distribution to the shareholders, you need to keep a record of the board meeting minutes and provide a dividend voucher for each shareholder.
You should also keep a record of the directors’ decision to declare the dividend, even if you’re the sole director. FreeAgent software, which we use at Integro, can help you produce the dividend paperwork and track payments.
If you’re unsure how much you can safely withdraw from your limited company, have a chat with your accountant before making the transfer.